A financial planner's 7 rules for holiday spending
Posted
Bobbi Rebell for Accredited Debt Relief
Email inboxes are already filling up with gift suggestions for the holidays. It may be hard to resist clicking on those links and going down the rabbit hole as you imagine all the smiles and warm feelings giving the perfect gift will bring.
That feeling is real, and it is part of why the holidays are so much fun. But it is also how budgets disappear. It’s not one big splurge (although that can also happen), but many small moments spent lingering on a purchase link and convincing yourself that the holidays are reason enough to “click” the buy button.
Retailers make it so easy. But then the elation deflates in January when the credit card bill comes due, and it looks nothing like the budget you set back in the fall. Accredited Debt Relief dives into what to do about it, but first, it helps to see how common this is.
How Many People Expect to Go Into Debt Over the Holidays?
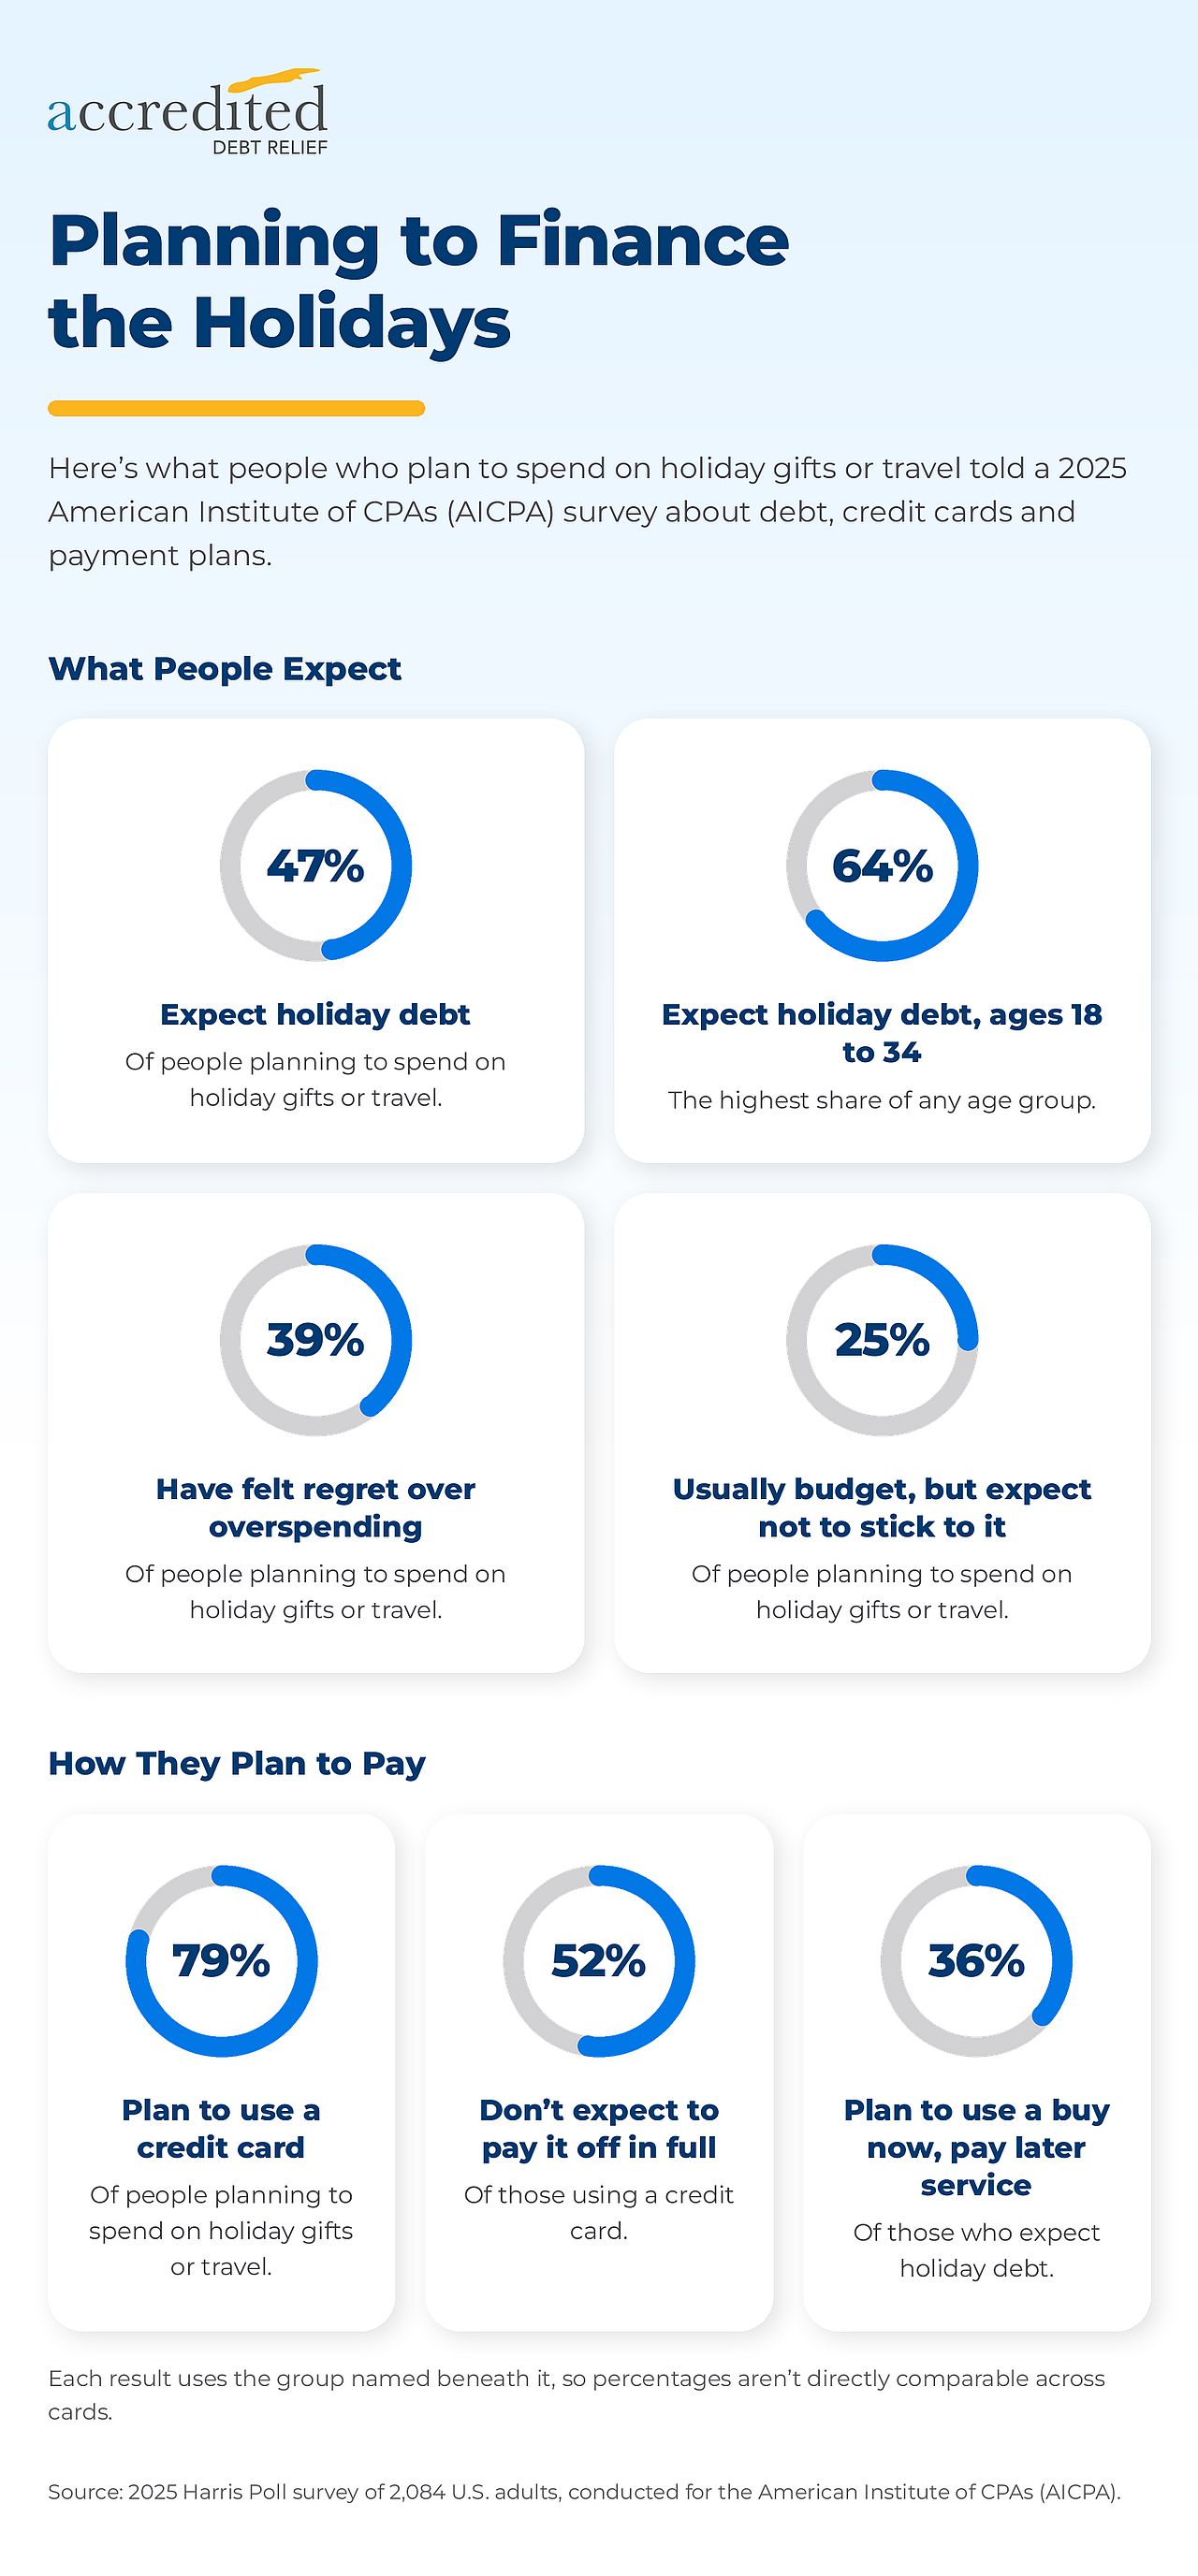
Unfortunately, if this sounds familiar, you are in good company. According to an October 2025 American Institute of CPAs (AICPA) survey, 47% of people expected to go into debt that holiday season. That number jumped to 64% among adults under 35. And 39% say they have felt real regret over past holiday overspending. A quarter of people who do make a holiday budget ahead of time do so, admitting that they probably won’t stick to that budget. They admit defeat before the season even gets underway.
Accredited Debt Relief
7 Rules for Holiday Spending
A plan is the missing piece. Here’s a framework for closing that gap, in the order you’ll need each rule.
Pick a headline number. Choose a number for the entire season as early as possible, ideally before you even start browsing. For example, you might decide that you are going to limit your holiday spending to between 1% and 1.5% of your annual income. Having a number decided on in advance that is well thought out and that you have made peace with will serve as guardrails to keep spending in line throughout the holidays.
Budget for all the holidays, not just your holidays or the big holidays. People tend to focus on the holidays that are important to their community, whether it be religious or cultural observances. They may home in on one or two big holidays that are important to them but be less aware of spending for secondary holidays that are important to relatives, friends and neighbors. Holidays that pop up can have just as much impact on budgets as those people plan for.
Gifts are just a slice of the pie. Spending on gifts may be a big part of your budget, but don’t overlook where a lot of money also goes. That can often include traveling to friends and family, or hosting them and all that entails. It can also include wrapping paper, cards, extra groceries for holiday meals, decorations and of course various Secret Santa and white elephant gifts that are expected at work and with friend groups. They may not feel like holiday spending because you aren’t actively purchasing a gift, but they need to be in your budget.
Pay with the money you have, not the money you hope to have. Given that 79% of people are planning to use a credit card and over a third consider using buy now, pay later, according to a May 2026 Accredited Debt Relief survey, it may be worth asking yourself honestly whether you are financing the holidays and not paying for them. If you are charging more than you can pay, splitting it into future payments extends the spending well into the spring. Is that the best use of your future money?
Decide: What is your debt breaking point? If you already know that you will be carrying debt into the new year, avoid denial and pretending it won’t happen. Honesty with yourself is hard, but it can take away anxiety and stress if you accept that you need a plan. Decide how much debt you are willing to carry and for how long. Figure out an actual payoff date, so you can be proactive not reactive.
Have a plan for what you will do if you do hit your budget limit before you are done gift shopping. It can happen even with the best intentions. This goes back to the important concept of self-honesty. Be prepared to look at what is left on your list and decide what can be handled differently or scaled back. That might mean getting creative with a homemade gift, or a note scheduling a shared experience that you can save for gradually. As an example, rather than giving a gift certificate to a treatment at a spa that you pay for now, make a nice personalized card promising to go to the spa together later in the winter or spring.
Debrief in January, and set up systems for next year’s holiday fund. The people who will feel the most calm about the holidays aren’t necessarily the ones who never overspend. They are the ones who look back honestly at what actually happened and then set up a small automatic transfer starting in January. That way December isn’t a last-minute scramble to find the money to pay for the holidays.
Holiday Spending FAQs
What if you are already in a spending pinch?
The first thing to keep in mind is that you are far from alone. The awareness of the precarious situation is a big step moving you in the right direction. Regret and frustration about money are common feelings during the season, and they are often buried just beneath the surface of smiles and holiday cheer. The goal now isn’t to second-guess every purchase or feel like a failure because you don’t have the financial resources to buy everything you want to have for your friends and family. Stop and reassess before you spend anything else. Look at what is left of the season and put in clear protections and guardrails for what you do have left. Understand where you will be financially, even if it isn’t a pretty picture. Seeing and accepting reality is often less stressful than avoiding it and imagining the worst.
What percentage of your income should go to holiday spending?
There’s no single right number, but a common benchmark to keep in mind would be roughly 1%–1.5% of annual income for the whole season. That includes gifts, food and travel expenses. That said, you are your own economy of one, and you should proactively think about what is the right number for you. What matters most is thoughtfully picking a number in advance and treating it as a real ceiling rather than a vague suggestion.
Is it bad to put holiday spending on a credit card?
It depends. If it is making it too easy to spend more than you intended, then yes, credit cards are not the best choice. Keep in mind that if you don’t pay off the balance when the bill arrives, it will turn into new, often high-interest debt. However, if you can pay the balance off, and there are rewards like cash back, using a credit card can be a smart move.